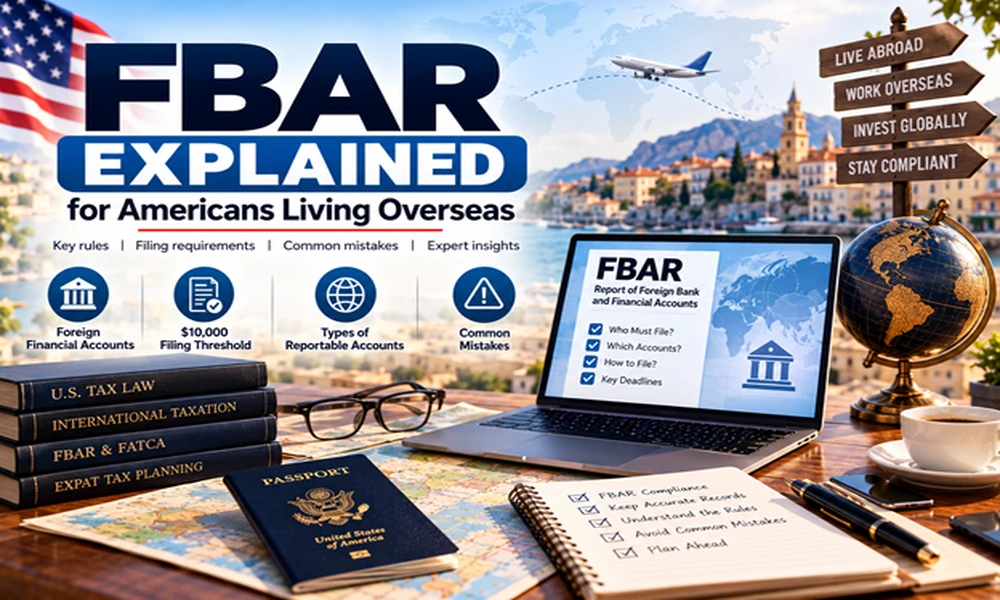

For Americans living outside the United States, managing foreign financial accounts can involve more than ordinary banking and investment decisions. U.S. citizens, residents and certain U.S. entities may have additional reporting obligations when they hold financial accounts outside the United States. One of the most important requirements to understand is the Report of Foreign Bank and Financial Accounts, commonly known as the FBAR.
The FBAR is filed electronically with the Financial Crimes Enforcement Network, or FinCEN, rather than being attached to a federal income tax return. Understanding when the filing requirement applies, which accounts may be reportable and what records need to be maintained can help taxpayers approach their annual reporting obligations accurately.
What Is an FBAR?
FBAR stands for Report of Foreign Bank and Financial Accounts. The requirement comes from the Bank Secrecy Act and is designed to provide the U.S. government with information about certain financial accounts held outside the United States.
A U.S. person generally must file an FBAR when they have a financial interest in, or signature or other authority over, one or more foreign financial accounts and the aggregate value of those accounts exceeds $10,000 at any time during the calendar year. The $10,000 threshold applies to the combined value of qualifying foreign accounts rather than separately to each account.
For example, someone with three qualifying foreign accounts valued at $4,000, $3,500 and $3,000 at their respective maximum points during the year may have an aggregate value exceeding the reporting threshold. The calculation and account valuation rules can be more detailed in practice, so taxpayers should maintain appropriate records rather than relying on an approximate balance.
Who May Need to File?
The FBAR rules apply to a broad definition of a U.S. person. This can include U.S. citizens and residents as well as certain domestic entities, including corporations, partnerships, limited liability companies, trusts and estates.
Living permanently outside the United States does not by itself remove the FBAR requirement. In fact, Americans who reside overseas may be particularly likely to maintain foreign bank or investment accounts for everyday expenses, employment income, retirement planning or business activities.
Whether a specific account is reportable depends on the applicable FBAR rules and the taxpayer’s relationship to the account.
What Types of Accounts Can Be Relevant?
Foreign financial accounts can include more than ordinary checking and savings accounts. Depending on the circumstances, reportable accounts can include foreign bank accounts, securities or brokerage accounts, mutual funds and certain other financial accounts. Recent IRS guidance also identifies certain annuities and insurance policies with cash value among the types of accounts that can fall within the FBAR framework.
An important point is that an account does not necessarily need to generate taxable income to be relevant for FBAR purposes. The IRS specifically notes that whether a foreign financial account produced taxable income does not determine whether it is a foreign financial account for FBAR reporting.
There are also exceptions. For example, certain accounts associated with individual retirement arrangements, qualifying retirement plans, governmental entities and U.S. military banking facilities may receive different treatment under the rules.
Common FBAR Mistakes
One common mistake is looking at each foreign account separately rather than considering the aggregate value of qualifying accounts. The $10,000 threshold is based on the combined value of applicable foreign financial accounts.
Another mistake is assuming that an account is irrelevant because it produced little or no income. FBAR reporting and income taxation are separate concepts. An account can potentially be subject to reporting even when it did not generate taxable income.
Taxpayers can also overlook accounts over which they have signature or other authority. Ownership is not the only consideration under the FBAR rules. Certain individuals who can control the disposition of funds in an account may have reporting obligations even when the circumstances differ from straightforward account ownership.
Currency conversion is another practical consideration for Americans abroad. Foreign account values must be considered in U.S. dollars for FBAR purposes, so maintaining reliable account statements and appropriate exchange-rate information can be important when preparing the report.
Why Accurate Records Matter
Good records make it easier to determine whether an FBAR filing is required and to provide the information needed for each reportable account.
The IRS states that records for reportable accounts should include information such as the account owner’s name, account number, the name and address of the foreign financial institution and the maximum account value during the relevant year.
Keeping monthly or periodic statements can therefore be useful, particularly for accounts where balances fluctuate significantly. Records can also help taxpayers distinguish between accounts that need to be reported and those that fall within an applicable exception.
When and How Is the FBAR Filed?
The FBAR is an annual report. It is generally due on April 15 following the calendar year being reported, with an automatic extension to October 15 if the April deadline is missed. The report must generally be submitted electronically through FinCEN’s BSA E-Filing System.
The FBAR should not simply be attached to a federal income tax return. It is a separate filing submitted through the Treasury Department’s FinCEN system.
It is also worth remembering that FBAR reporting can exist alongside other international tax reporting requirements. For example, some taxpayers may separately have obligations involving Form 8938 under FATCA rules. Meeting one reporting requirement does not automatically mean that every other foreign-asset reporting requirement has been satisfied.
A Professional Perspective from Mitchell Propster
Expat Tax Firm identifies Mitch Propster as its founder and lists him as a CTC and team leader. The firm’s published services include FBAR and foreign reporting, FATCA compliance, foreign income reporting, U.S. expat tax returns and expat tax planning.
From the firm’s published service information, FBAR forms part of a broader approach to U.S. expat tax compliance. Its services are aimed at individuals and business owners dealing with U.S. and international tax requirements, including Americans living abroad and people with international financial interests.
More information about the firm’s services is available through Expat Tax Firm, while Mitchell Propster’s professional background can be reviewed through his LinkedIn profile.
The Bigger Picture
FBAR is only one part of the international tax landscape for Americans overseas. Foreign income, FATCA reporting, foreign businesses, investments and other international financial arrangements can create separate considerations.
The most important starting point is understanding that the $10,000 FBAR threshold applies to the aggregate value of qualifying foreign financial accounts at any point during the calendar year. Maintaining accurate account records and reviewing reporting obligations annually can make the process more straightforward.
Because international tax rules can depend on individual circumstances, taxpayers with complex foreign accounts or financial arrangements may benefit from consulting a qualified tax professional before filing. This is particularly relevant when account ownership, signature authority, foreign businesses or multiple reporting requirements are involved.